Will Florida Amendment 3 Lower Your Mortgage Payment?
Florida’s approved Amendment 3 may reduce the property-tax portion of an eligible homeowner’s future housing costs, but it does not automatically lower a mortgage payment on January 1, 2027. A servicer’s escrow review, insurance costs and any escrow shortage also affect the amount due. Keep paying the amount shown on your mortgage statement.
Reviewed November 11, 2026.
When do the property-tax changes begin?
The Florida Department of Revenue confirms that Amendment 3 starts with the 2027 tax roll. For qualifying homeowners covered by the larger-exemption schedule, the homestead exemption for non-school levies increases to up to $150,000 in 2027 and up to $250,000 in 2028. School taxes retain their separate $25,000 exemption. The change does not reduce your 2026 property-tax bill.
See the Department of Revenue’s November 5 bulletin. Implementation guidance is still developing.
Which part of my payment could change?
A typical mortgage payment may include principal, interest, mortgage insurance and escrow deposits for taxes and homeowners insurance. A property-tax exemption changes taxable property value. It does not change your loan’s principal balance or contractual interest rate.
The Consumer Financial Protection Bureau explains how taxes and insurance can change a mortgage payment. The timing and amount depend on your account.
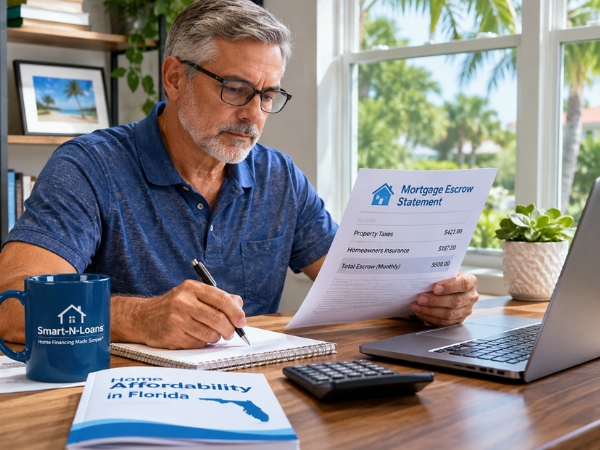
Illustrative escrow statement; amounts shown are examples, not a payment quote. A property-tax change may affect escrow after the servicer reviews the account. Keep paying the required statement amount until the servicer confirms a change.
Why might the payment stay the same or rise?
Lower taxes can be offset by higher insurance premiums, an escrow shortage repayment or other changes. A servicer also estimates future bills when performing an escrow analysis. Do not assume that an amendment’s effective date and your payment-change date are the same.
A simple budgeting example
Suppose a future finalized annual property-tax bill is $1,200 lower. Dividing $1,200 by 12 produces a $100 monthly budgeting equivalent. That is an illustration, not an Amendment 3 savings estimate or a promised payment reduction. A $900 annual insurance increase would use $75 of that monthly equivalent before shortage repayments or other changes.
Use your actual tax bill, insurance renewal and escrow analysis rather than relying on this example.
What should homeowners ask their servicer?
When is my next annual escrow analysis?
What tax and insurance amounts does the current analysis use?
Is a shortage or deficiency included in my payment?
What documentation is needed to review a changed property-tax bill?
When would any revised required payment begin?
Request an explanation in writing and retain your tax bill and escrow statement. Continue making the required payment until the servicer confirms a change.
Buying a Florida home? Estimate your own taxes
The seller’s tax bill may reflect years of Save Our Homes protection and exemptions that do not automatically become yours. Ask the county property appraiser for a purchase-specific estimate and confirm which residency rules apply.
For people who were not permanent Florida residents by December 31, 2026, the larger exemption generally begins with the fifth year of homestead exemption. Buying a home alone does not settle eligibility. Do not build an affordability budget around an exemption you have not confirmed.
For the statewide amendment timeline, read FL Homes Magazine’s master homestead guide. Read our Florida homestead and property-tax guide for the differences between assessed value, exemptions and portability.
Common mortgage and escrow questions
Should I reduce my payment myself?
No. Use the payment amount your servicer requires. An expected future tax benefit is not permission to pay less.
Will everyone save the same amount?
No. Exemption eligibility, assessed value, existing benefits and local tax rates differ. Non-ad valorem assessments are separate. A lower taxable value does not guarantee a specific reduction in the total bill.
Do I need to refinance to receive a homestead exemption?
Homestead eligibility is administered by the county property appraiser. Refinancing is a separate financing decision. Ask about your property-tax eligibility directly rather than assuming a new loan is needed.
What if I do not have an escrow account?
You remain responsible for paying property taxes and insurance directly when due. Review the actual tax bill and keep enough money reserved for all ownership costs.
Review the whole housing budget
Bring your mortgage statement, escrow analysis, insurance renewal and property-tax documents to a conversation about affordability. Kelly and Ray can help you understand how those costs fit a financing decision; your servicer controls escrow administration and your county property appraiser determines exemption eligibility.
Call Kelly and Ray: 321-321-9455. Review our Florida mortgage programs or visit retirement mortgage planning for related education.
Smart-N-Loans is an educational and marketing brand, not a lender. Mortgage services are provided through Equity Smart Home Loans. Kelly Nadeau, Licensed Florida Broker BK3344334, NMLS #1027618; Ray Nadeau, Licensed Florida Broker BK3344407, NMLS #1027617. Loan Officers — Licensed in Florida. Equity Smart Home Loans, NMLS #856170, Florida License MBR-2341, DRE #01906808. 1499 Huntington Dr, Suite 500, South Pasadena, CA 91030. Equal Housing Lender.
Not a commitment to lend. All financing is subject to credit approval, underwriting, property eligibility and applicable lender and program requirements. Programs and availability may change. This article provides general education, not tax or legal advice. Confirm property-specific questions with your county property appraiser and an appropriate tax or legal professional.
Trusted Resources
Explore our related companies. These businesses share ownership and provide separate services.
FL Homes Magazine — Florida housing and homeowner education.
Certainly Sold — Central Florida real estate brokerage.
Elder Placement Agency — Senior housing and placement guidance.
Agency AI Lab — Business marketing and automation resources.